Asset Location vs. Asset Allocation in Financial Planning
Even the healthiest seed will struggle if it is planted in the wrong type of soil. Investments can work the same way since some assets benefit from being placed in specific vehicles, particularly when it comes to how they are taxed. This idea is often referred to as “asset location,” which doesn’t refer to where assets are held geographically. Instead, it is the practice of placing each investment in the account type where it can grow most efficiently. This might include a taxable brokerage account, a tax-deferred account like a traditional IRA or 401(k), or a tax-free account like a Roth IRA.
This matters because most investors spend a lot of time thinking about what to invest in. But where you hold those investments can matter just as much. Unlike asset allocation, which is how investors diversify across asset classes like stocks and bonds, the main idea behind asset location is for investors to maximize their after-tax outcomes. After all, this is the amount that matters for your financial planning needs. Ultimately, the goal of asset location is to maximize the likelihood of reaching your financial goals over your lifetime. What important factors should investors consider today?
Matching the right investment vehicle and account type matters
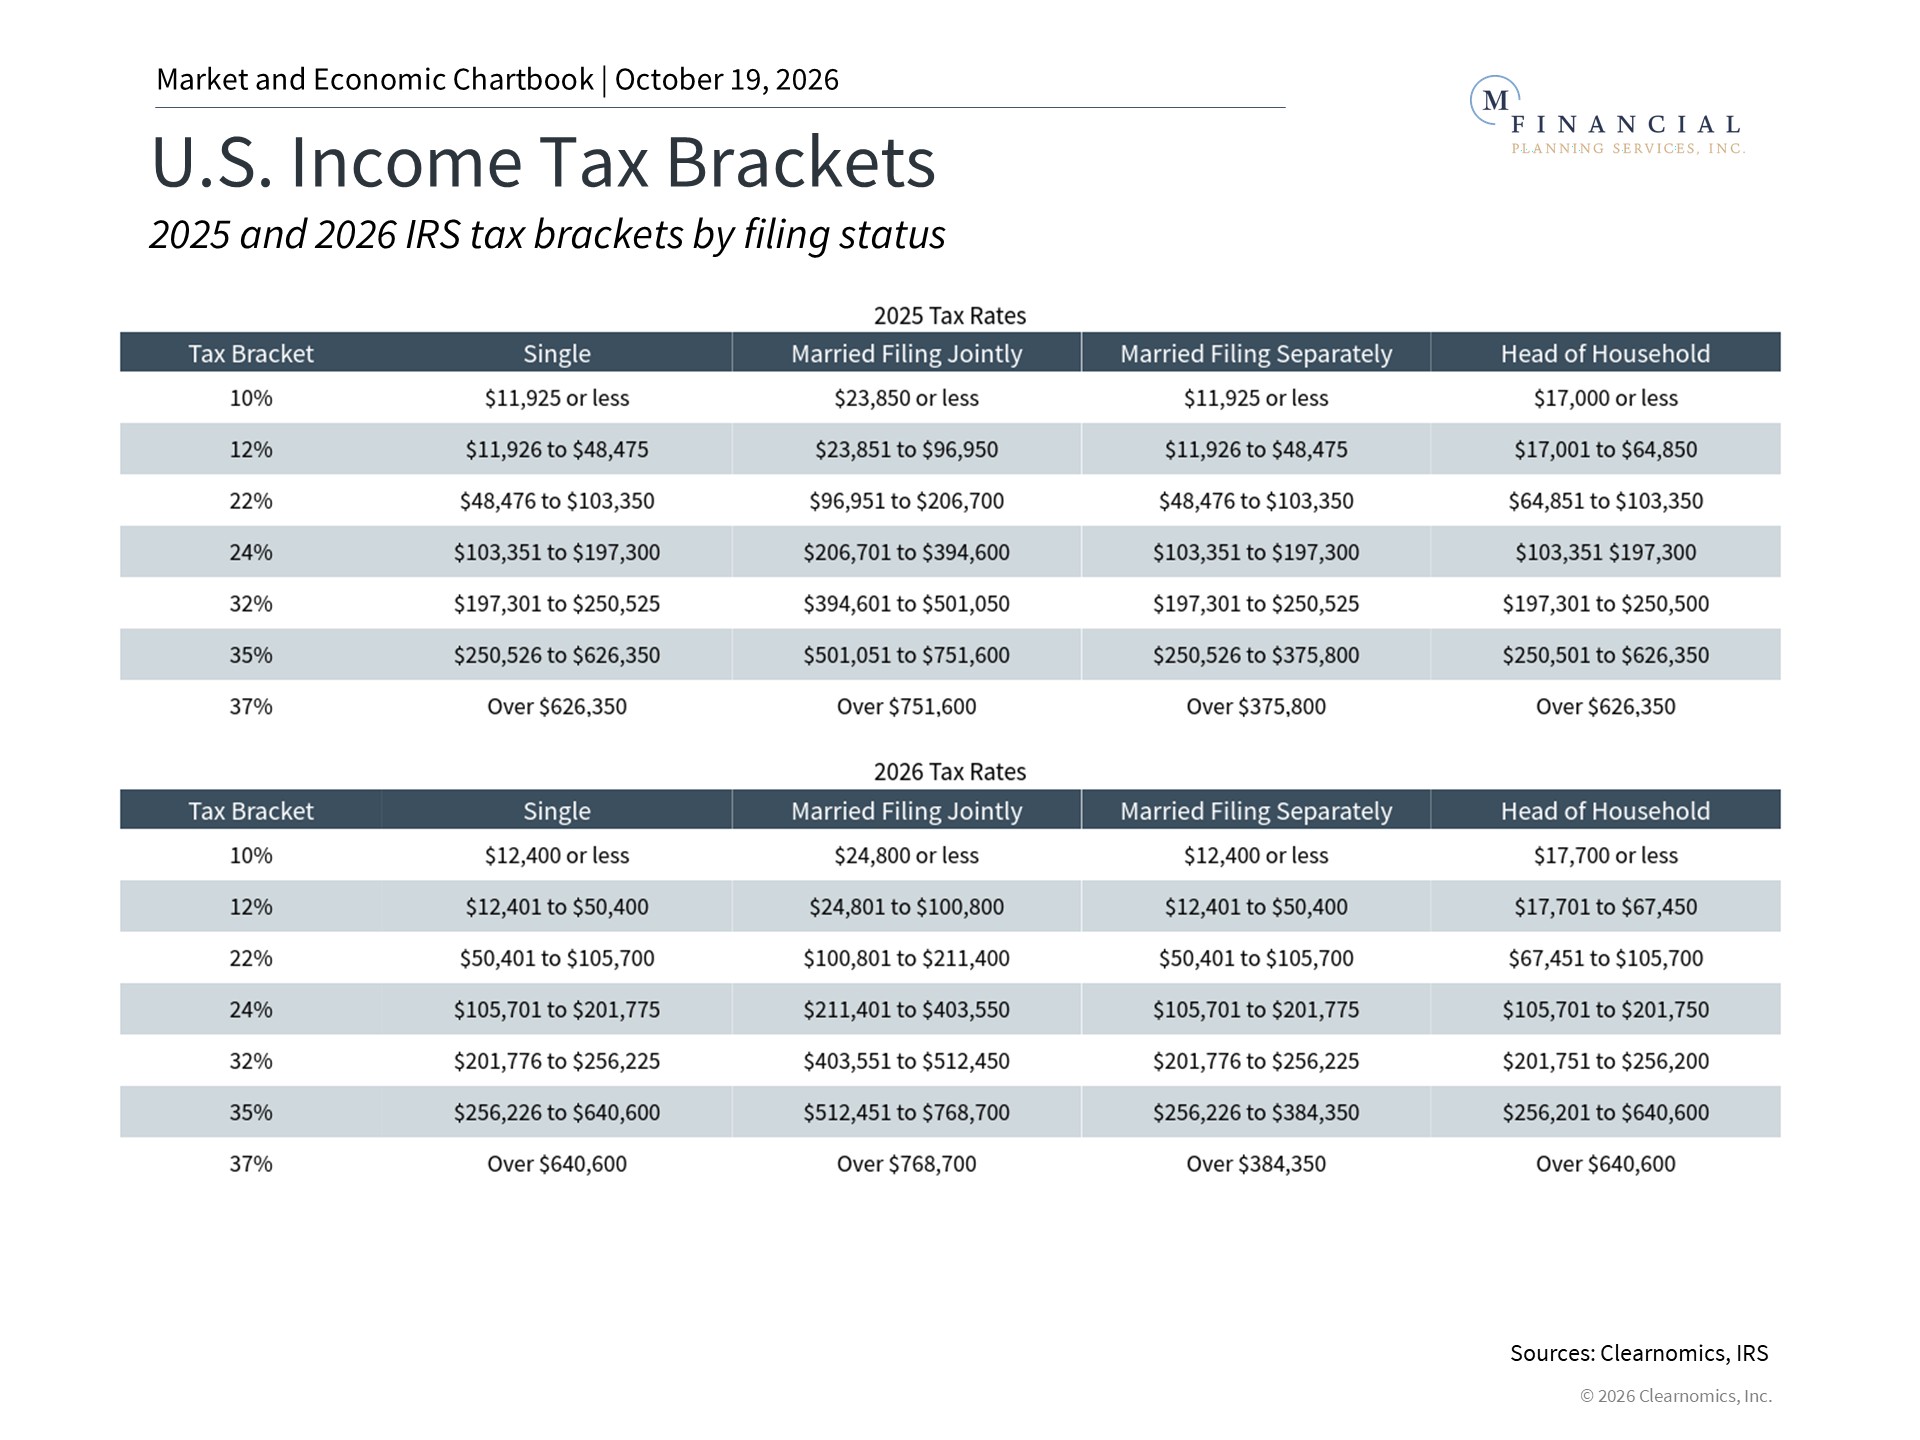
Taxable accounts, such as traditional brokerage accounts, are flexible and liquid in that they have no withdrawal age restrictions, no contribution limits, and no early withdrawal penalties. The main drawback is that these accounts are subject to current taxation on dividends, interest, and realized capital gains. In particular, interest and short-term gains are taxed at ordinary income rates, while qualified dividends and long-term capital gains are taxed at preferential rates.1 The accompanying chart shows the federal income tax rates and brackets for 2026 which peak at 37%, while long-term capital gains tax peaks at 20%.2
Given this, taxable accounts are generally well-suited for tax-efficient or tax-exempt investments, such as low-dividend stocks held for the long run, and exchange traded funds (ETFs) with low turnover. Municipal bonds are another example, since their interest is generally exempt from federal, and in some cases state income tax. Although these accounts don’t come with built-in tax benefits, certain strategies, such as tax loss harvesting or charitable gifting, can help manage annual taxes.
Tax-advantaged accounts can cover a variety of vehicles such as Roth IRAs, employer-sponsored 401(k) plans, and more. For Roth IRAs, for instance, contributions are non-deductible, but earnings can grow tax-free, and qualified withdrawals are also not taxable. This can make Roth accounts particularly attractive for assets with higher expected growth, since most of the potential appreciation can compound without creating a future tax liability.
This is different from traditional IRAs, which allow pre-tax contributions while withdrawals are taxed at ordinary income rates. Since all of the earnings are reinvested tax-free, the aggregate balance can grow faster than in a standard taxable account. Such accounts are ideal for income-heavy or tax-inefficient assets that would otherwise generate annual taxable income. Examples include high-yield fixed income securities, high-dividend stocks, and Real Estate Investment Trusts (REITs).
Planning considerations for long-term strategies
Investors should always begin building their strategy by considering their individual needs, including liquidity, major expenses, higher education, retirement income, and time horizon, to help determine the right mix. This includes weighing the pros and cons of strategically holding funds in specific types of accounts.
One major consideration, for example, is the balance between long-term investing and short-term liquidity, or locking money away for a longer period of time but losing the ability to access those funds when needed. A Roth IRA, for instance, can serve as a liquidity valve because original contributions can be withdrawn tax- and penalty-free at any time.3
For estate planning, there are many other considerations. For example, taxable brokerage accounts are traditionally seen as short-term liquidity pools and can be effective vehicles for transferring wealth upon death because assets receive a step-up in basis when transferred, so heirs avoid larger capital gains taxes and preserve more wealth for transfer.4
Additionally, investors can match assets to specific financial purposes across both Health Savings Accounts (HSAs) and education funds. HSAs offer a unique triple-tax advantage, making it an excellent vehicle for long-term growth if you can pay current medical bills out of pocket and let the balance grow over time. Similarly, for education funding goals, investors can use 529 plans to grow assets tax-free.
Future tax laws can change which may impact asset location strategies. Investors should consider the increased management complexity and time required to monitor and adjust this strategy over time.
Finally, taxes are only one consideration when it comes to financial planning, so asset location should support investors’ broader financial objectives, not just lower taxes in the current tax year. For retirees, this can mean optimizing asset placement to support tax-efficient withdrawals by drawing from taxable accounts first to preserve tax-free growth. For accumulators, it can also mean magnifying after-tax compounding and turning incremental savings into greater lifetime value.
Instead of viewing these accounts in isolation, investors can unlock their full tax efficiencies by treating them as an interconnected system. When it comes to investing and retirement planning, asset location considerations play an important role in your investment strategy. While many investors focus on fine-tuning what assets they own, the decision of where to place those assets is also important.
The bottom line? Asset location can support financial goals, bridging investment strategy and tax planning. By aligning the right account structures with the right asset types, and viewing these choices through the lens of broader financial planning, investors can potentially enhance after-tax returns without changing their overall investment mix.
References
1. https://www.irs.gov/taxtopics/tc409
2. https://www.irs.gov/filing/federal-income-tax-rates-and-brackets
3. https://www.irs.gov/publications/p590b
4. https://www.irs.gov/publications/p559
Securities and advisory services offered through LPL Financial, a registered investment advisor. Member FINRA / SIPC. Financial planning offered through M Financial Planning Services, a Registered Investment Advisor and a separate entity.
This material is for general information only and is not intended to provide specific advice or recommendations for any individual. There is no assurance that the views or strategies discussed are suitable for all investors or will yield positive outcomes. Investing involves risks including possible loss of principal. No investment strategy or risk management technique can guarantee return or eliminate risk in all market environments Any economic forecasts set forth may not develop as predicted and are subject to change.
References to markets, asset classes, and sectors are generally regarding the corresponding market index. Indexes are unmanaged statistical composites and cannot be invested into directly. Index performance is not indicative of the performance of any investment and do not reflect fees, expenses, or sales charges. All performance referenced is historical and is no guarantee of future results.
This information is not intended to be a substitute for specific individualized tax or legal advice. We suggest that you discuss your specific situation with a qualified tax or legal professional.
Bonds are subject to market and interest rate risk if sold prior to maturity. Bond values will decline as interest rates rise and bonds are subject to availability and change in price.
U.S. Treasury securities are guaranteed by the federal government as to the timely payment of principal and interest. The principal value of Treasury securities and other bonds fluctuates with market conditions.
International investments carry additional risks, which include differences in financial reporting standards, currency exchange rates, political risks unique to a specific country, foreign taxes and regulations, and the potential for illiquid markets. These factors may result in greater share price volatility.
This material was prepared by Clearnomics, Inc., who is not affiliated with the named financial professional, firm or broker/dealer.
There are two keys to understanding asset location. The first is that investment accounts can be broadly characterized as taxable and tax-advantaged. Taxable accounts are those where gains are subject to taxes such as ordinary income rates, capital gains rates, and more, depending on the specific circumstances. In contrast, tax-advantaged accounts help to shield gains from taxes but come in many different forms with specific rules.
The second key is that investments can differ in how “efficient” they are when it comes to taxes. An investment is considered tax-inefficient when a share of its return is lost to taxes each year, usually because it produces income taxed at ordinary income rates, such as interest from corporate bonds, or because it frequently distributes short-term capital gains, as some funds do.
The goal of asset location then is to hold tax-inefficient investments in accounts where their income is sheltered from taxes, and use taxable accounts for other investments, including those that will likely be held long-term or already receive relatively favorable tax treatment.
While this concept may seem simple, it requires careful planning in practice because there are often limits to the amount of investments made in tax-advantaged vehicles and rules around when funds can be withdrawn.
Account types provide multiple opportunities